

While the U.S. economy has remained resilient entering the fall, the consumer backdrop has become increasingly challenging for the restaurant sector. In August, real personal consumption expenditures increased 0.6% month over month, while real disposable personal income was unchanged, reflecting limited purchasing-power growth. The Federal Reserve raised the federal-funds rate by 25 basis points to 3.75%–4.00% on September 16 as inflation remained above its 2.0% target. August headline CPI-U increased 3.4% year over year, including a 16.3% rise in energy prices, while unemployment stood at 4.1%. According to Moody’s Analytics Chief Economist Mark Zandi, the Iran conflict has cost U.S. households approximately $2,000 each, comprised of $1,100 in higher energy costs, $540 in interest expenses and $360 in military costs, disproportionately burdening lower-income consumers in an increasingly K-shaped economy. Against this backdrop, QSR and fast-casual operators are emphasizing affordability and value, while polished casual and fine-dining concepts are prioritizing differentiated experiences to reinforce their appeal relative to at-home dining.
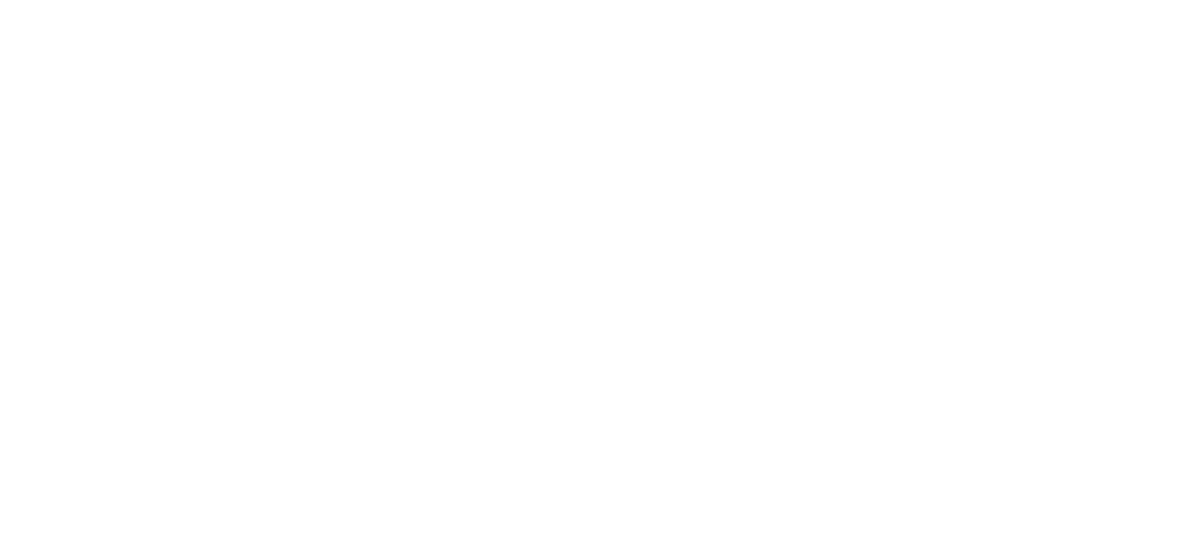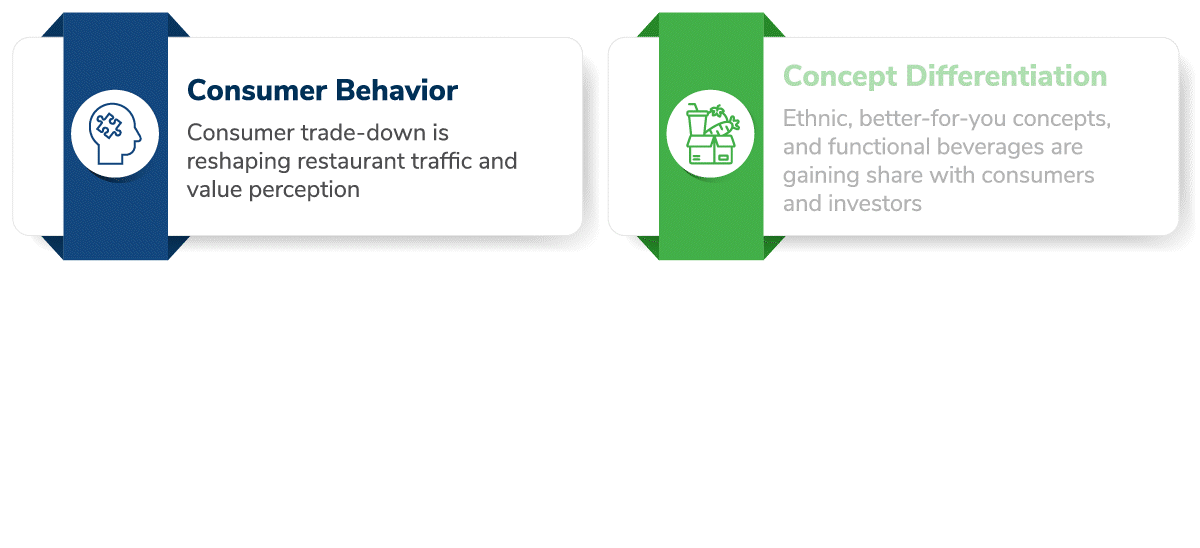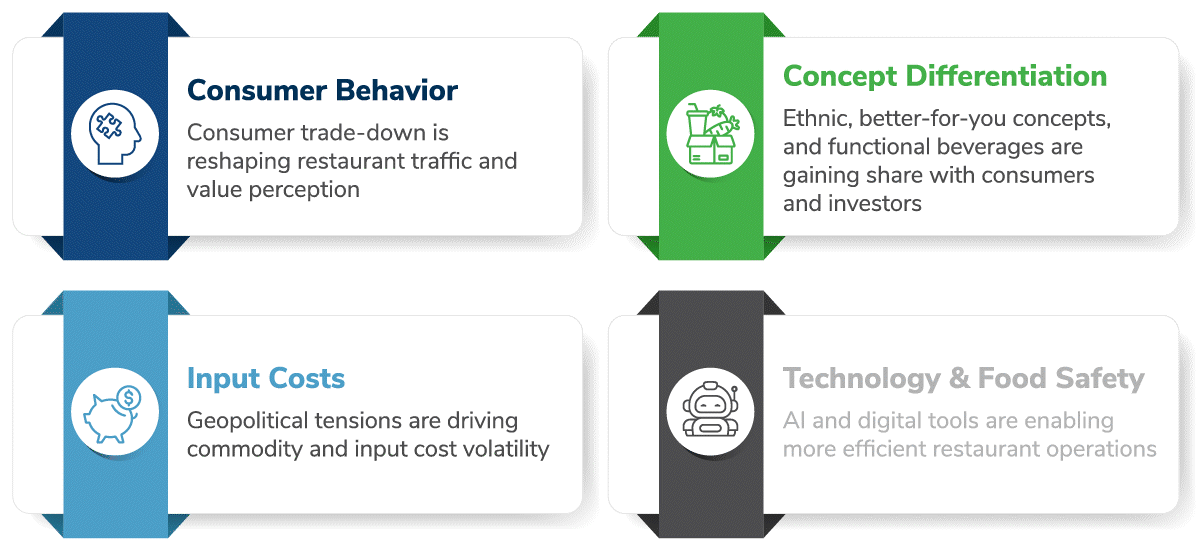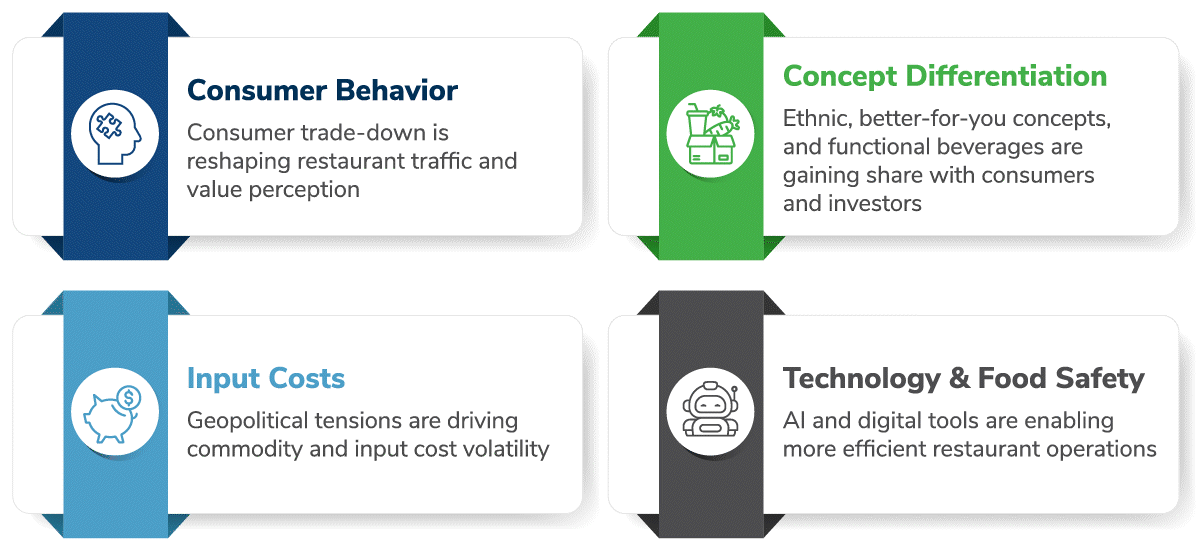
The broader U.S. restaurant M&A environment has also exhibited bifurcated activity, with transaction value increasing despite a modest decline in deal volume. For transactions involving a U.S. acquirer and U.S. target, announced transaction value increased nearly 50% to ~$320 billion in the first half of 2026, while deal count declined 2% from the comparable 2025 period. Restaurant activity nevertheless included several notable transactions: Yum! Brands agreed to sell Pizza Hut for $2.7 billion in aggregate to LongRange Capital outside China and Yum China in China, with LongRange completing its acquisition on September 1; Minor Food Group and Serruya Private Equity acquired Bonchon from VIG Partners and the founder’s family; and TSG Consumer made a strategic investment in Los Tacos No. 1. Buyers continue to emphasize durable unit economics, brand differentiation and credible development runways. The supply of sponsor-owned assets also remains elevated: PwC estimated that at the current rate of private equity exits, it would take approximately nine years to clear existing portfolio company inventory, supporting continued use of alternative liquidity solutions.
Restaurant operating data remained mixed but showed improvement in August. In the National Restaurant Association’s monthly tracking survey, 51% of operators reported higher same-store sales year over year and 31% reported lower sales; however, 46% reported lower customer traffic, compared with 43% reporting higher traffic. Inflation in commodity input costs, energy and labor continued to pressure restaurant margins, reinforcing the importance of productivity, disciplined development and restaurant-level returns. Investor underwriting has accordingly become more selective, with the greatest emphasis on scalable concepts, healthy unit economics, manageable leverage and visible unit-growth potential. Financial pressures remain particularly evident among leveraged franchisee operators, with at least 10 significant multi-unit restaurant franchisee bankruptcy filings through mid-September, collectively affecting several hundred restaurant locations.
As of September 30, 2026, the median LTM EV/EBITDA multiple was 14.6x for the defined 31-company U.S.-listed, North America-focused public restaurant peer group. Over the preceding 12 months, the S&P 500 Restaurants Sub-Industry Index declined 16.2% on a price-return basis, compared with a 14.4% increase in the S&P 500, representing 30.6 percentage points of underperformance by the restaurant sector. This report endeavors to synthesize macroeconomic, operating, transaction and public-market data into decision-relevant themes for restaurant investors, lenders and operators, emphasizing factors most likely to influence performance and strategic activity over the coming quarters.


Stay Ahead with Kroll
Investment Banking
Kroll’s Investment Banking practice specializes in middle-market transactions, offering tailored M&A advisory and capital-raising services to private equity firms, corporations, and business owners.
Consumer, Food, Restaurant and Retail Investment Banking
Consumer, Food, Restaurant and Retail expertise for middle-market M&A transactions.
Mergers and Acquisitions (M&A) Advisory
Kroll’s top ranked M&A Advisory practice spans sell-side, buy-side, due diligence, deal strategy and structuring, and capital raising.